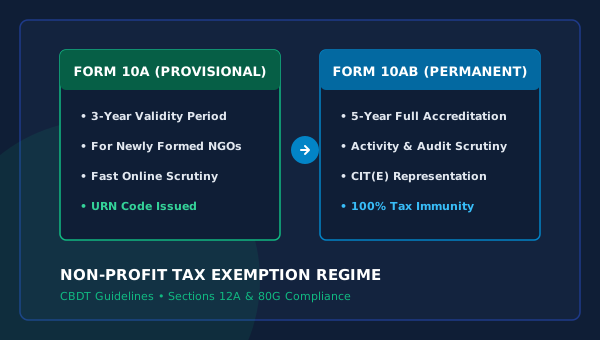
The Central Board of Direct Taxes (CBDT) transitioned the entire regime for charitable trust exemptions under Sections 12A and 80G into a digital, time-limited accreditation structure.
Non-profit trustees and Section 8 directors must understand the strict distinction between provisional registration in Form 10A and regular 5-year certification in Form 10AB.
Understanding the Two-Tier Exemption Structure
Under the revised provisions of the Income Tax Act, 1961:
- Form 10A (Provisional Registration): Newly established trusts or Section 8 companies that have not yet initiated charitable operations apply for provisional approval. This provisional certification is valid for 3 years.
- Form 10AB (Permanent 5-Year Registration): Within 6 months of commencing charitable activities, or at least 6 months prior to the expiration of the 3-year provisional tenure, the NGO must apply for regular registration in Form 10AB.
Key Documentation Required for Form 10AB Scrutiny
The Commissioner of Income Tax (Exemptions) conducts detailed scrutiny before granting the 5-year accreditation. Crucial documents include:
- Certified copies of the registered Trust Deed / MOA showing exclusively non-commercial charitable objectives.
- Comprehensive activity reports with photographic and verifiable beneficiary proof.
- Audited balance sheets, income & expenditure accounts, and donation registers for past operational years.
- List of trustees with PAN, address proofs, and statutory non-conflict declarations.
Maintaining clean accounting ledgers and ensuring donations are spent strictly on objects defined in the charter ensures smooth processing without rejection notices.